
on rarefiedtech.com fintech is a useful starting point for understanding how technology is reshaping the way individuals, businesses, and financial institutions manage money. Fintech has moved well beyond the idea of simply putting banking services on a smartphone. Today, it encompasses digital payments, artificial intelligence, blockchain, automated investing, financial analytics, lending platforms, identity verification, and an expanding ecosystem of digital financial infrastructure. RarefiedTech.com’s fintech coverage reflects this broad landscape, with its site organizing fintech as one of its principal content categories.
What makes this subject especially interesting is the speed at which financial technology is becoming part of ordinary life. Sending money, paying a merchant, applying for financing, monitoring spending, or investing can now happen in seconds rather than through lengthy paper-based processes. At the same time, convenience introduces important questions about cybersecurity, privacy, regulation, financial literacy, and responsible innovation. Exploring on rarefiedtech.com fintech therefore means looking not only at exciting technologies, but also at the forces that determine whether those technologies genuinely improve financial experiences.
Understanding the Fintech Landscape Covered by RarefiedTech
Fintech, short for financial technology, describes the use of technology to create, improve, automate, or deliver financial products and services. Its reach is enormous. Mobile wallets, online banking applications, payment gateways, peer-to-peer transfers, robo-advisors, digital lending platforms, blockchain networks, fraud-detection systems, and financial management tools can all fall under the fintech umbrella. RarefiedTech’s dedicated fintech category demonstrates this breadth, featuring subjects ranging from payment innovation and digital transactions to software, trading, and emerging financial technologies.
The importance of on rarefiedtech.com fintech lies partly in connecting these individual technologies to a larger story. A payment application is not merely another smartphone tool; it represents a shift in consumer expectations around speed and accessibility. Similarly, automated financial analysis is not simply a software upgrade. It can change how companies assess risk, allocate resources, communicate with customers, and make operational decisions. Looking at fintech through this wider lens helps readers understand why seemingly small innovations can have significant consequences across the financial ecosystem.
Another important feature of modern fintech is the blending of financial services with technologies originally developed for other industries. Artificial intelligence can analyze enormous volumes of financial data, cloud computing can support scalable financial infrastructure, and biometric authentication can strengthen identity verification. Blockchain technology introduces another model for recording and transferring value. RarefiedTech’s fintech-related material highlights several of these themes, including AI-powered analytics, automated payments, blockchain security, and smarter lending technologies.
This convergence is creating an industry in which finance and technology are increasingly difficult to separate. Financial companies need sophisticated technology to compete, while technology companies increasingly participate in activities that have traditionally belonged to banks and other financial institutions. For readers researching on rarefiedtech.com fintech, this intersection is one of the most important concepts to understand because it explains why fintech developments can affect everything from everyday purchases to international business.
Digital Payments and the Rise of Frictionless Finance
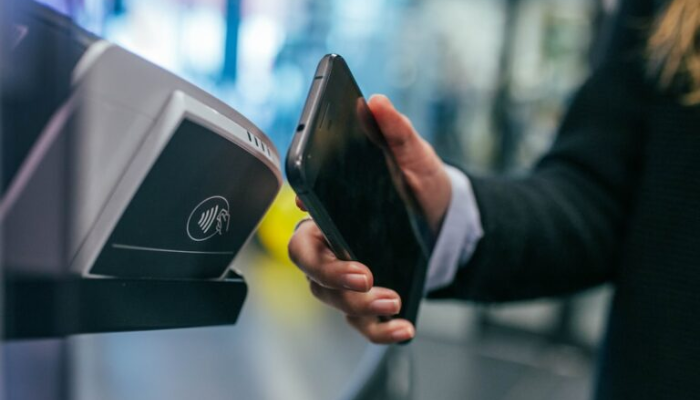
Digital payments are among the clearest examples of fintech becoming part of everyday life. Consumers increasingly expect transactions to be fast, convenient, traceable, and available through multiple devices. Mobile payment applications, digital wallets, online checkout systems, contactless payments, and peer-to-peer transfer services have reduced many of the practical barriers associated with traditional payment methods. RarefiedTech has specifically explored payment fintech solutions, describing technologies such as mobile payments, blockchain platforms, and peer-to-peer transfer applications as important components of the modern financial technology ecosystem.
The significance of this transformation goes beyond convenience. Businesses can benefit from faster settlement, automated reconciliation, improved transaction records, and new ways of serving customers. Small businesses may gain access to digital payment infrastructure without needing the same physical resources as larger organizations. Online merchants can serve customers across geographical boundaries, while freelancers and remote workers can increasingly rely on digital systems to receive payments. As these systems mature, the payment experience becomes less visible to users while becoming more sophisticated behind the scenes.
However, frictionless payments also create a new set of challenges. A transaction that takes only a few seconds can still involve complex authentication, encryption, fraud detection, data processing, and regulatory checks. Users may not see these mechanisms, but they are crucial to maintaining confidence in digital finance. If security fails, the same speed that makes digital payments attractive can allow fraudulent activity to occur rapidly.
This is why the future of payment fintech is not simply about making transactions faster. The industry must balance speed with security, convenience with privacy, and innovation with consumer protection. Effective fintech platforms make these protections as seamless as possible while still giving users meaningful control over their financial information and transactions.
Artificial Intelligence, Automation, and Smarter Financial Decisions
Artificial intelligence is becoming one of the most influential technologies in fintech because financial services generate enormous amounts of structured and unstructured data. AI systems can help identify patterns, detect unusual transactions, personalize financial recommendations, automate customer support, and support risk assessment. RarefiedTech’s recent fintech coverage identifies AI-powered financial analytics as one of the developments influencing the direction of digital finance.
For consumers, AI can make financial applications more responsive and personalized. Instead of simply displaying a list of transactions, a modern financial platform may categorize spending, identify recurring expenses, highlight unusual activity, or provide projections based on historical behavior. For businesses, automated analytics can help decision-makers identify trends and process information that would otherwise require substantial manual effort.
Automation can also improve operational efficiency. Financial institutions and fintech companies routinely deal with repetitive processes such as document verification, transaction monitoring, customer onboarding, and reporting. Automating portions of these workflows can reduce processing time and allow human employees to concentrate on complex cases that require judgment and contextual understanding.
Yet AI should not be treated as an infallible financial authority. Algorithms can inherit biases from their training data, make incorrect predictions, or produce recommendations that users misunderstand. Financial decisions can have serious consequences, so transparency and human oversight remain important. The most responsible approach is to use AI as a decision-support technology rather than assuming that every automated output is automatically correct.
For anyone following on rarefiedtech.com fintech, this distinction is particularly valuable. The most interesting AI developments are not necessarily the ones with the most dramatic marketing claims. The stronger innovations are those that solve genuine problems, improve accuracy or efficiency, and provide clear benefits without sacrificing transparency or accountability.
Blockchain, Digital Assets, Security, and the Regulatory Equation
Blockchain has become closely associated with fintech because it introduced a different approach to recording transactions and coordinating digital ownership. Instead of relying exclusively on centralized databases, blockchain networks can distribute records across multiple participants. This concept has applications ranging from digital assets to settlement infrastructure and certain forms of identity and transaction verification.
RarefiedTech’s fintech content has addressed blockchain-based security and digital financial developments alongside broader payment innovations. Its broader website also features fintech topics involving cryptocurrency and stablecoin liquidity, illustrating how digital assets remain part of the evolving conversation around financial technology.
The potential benefits of blockchain include transparency, programmability, and the possibility of reducing friction in selected financial processes. Smart contracts, for example, can automate predefined actions when specified conditions are met. Stablecoins can provide blockchain-based representations of value designed to maintain relatively stable prices, although their risks and regulatory treatment vary considerably by jurisdiction and structure.
Security, however, cannot be reduced to the word “blockchain.” A blockchain network may have particular security characteristics while applications, exchanges, wallets, smart contracts, or user accounts built around it can still contain vulnerabilities. Users therefore need to distinguish between the underlying technology and the individual service through which they access it.
Regulation is equally important. Financial technology operates in a highly regulated environment because mistakes and abuses can affect people’s savings, credit, privacy, and economic security. Regulators around the world continue to consider how existing rules should apply to digital assets, automated decision-making, payments, data sharing, and emerging financial services. The challenge is finding a balance: regulation should reduce harmful behavior and protect consumers without unnecessarily preventing useful innovation.
The regulatory question will remain central to on rarefiedtech.com fintech and to the fintech industry generally. Sustainable innovation depends on trust, and trust is difficult to maintain when users do not understand who is responsible for a financial service, how their information is handled, or what protections exist if something goes wrong.
The Future of Fintech: Accessibility, Integration, and Responsible Innovation
The next phase of fintech is likely to be defined less by isolated applications and more by integration. Financial services are increasingly becoming embedded into shopping platforms, business software, communication tools, marketplaces, and other digital environments. Instead of visiting a dedicated financial institution for every transaction, users may encounter financial services precisely where they need them.
This trend can make finance more accessible. Entrepreneurs may obtain business services through digital platforms, workers may receive payments through international financial infrastructure, and consumers may manage spending and savings through increasingly integrated applications. RarefiedTech’s fintech coverage reflects this wider movement by discussing subjects such as digital transactions, payment technologies, lending, software innovation, and financial access.
Financial inclusion is particularly important. Traditional financial systems have not always served every population equally well. Digital technology can lower certain barriers by reducing the need for physical branches, simplifying onboarding, and creating alternative ways to access payments and financial services. However, technology alone does not guarantee inclusion. Users still need affordable connectivity, digital literacy, secure identification, appropriate consumer protections, and financial products designed around genuine needs.
The future will also demand greater attention to responsible design. A financial application should not merely encourage users to transact more frequently. It should help them understand what they are doing. Clear fees, understandable risk disclosures, strong authentication, accessible customer support, and sensible defaults can make a substantial difference.
This human-centered perspective is important because financial technology ultimately exists to serve people. The most successful fintech products may not be the ones with the longest feature lists. They may be the ones that quietly eliminate frustrating processes, reduce unnecessary costs, provide useful information, and help users make better decisions.
Conclusion: What on rarefiedtech.com fintech Reveals About the Future of Finance
on rarefiedtech.com fintech provides a useful lens through which to examine one of the fastest-changing areas of modern technology. From digital payments and automated financial services to artificial intelligence, blockchain, lending, cybersecurity, and financial inclusion, fintech is transforming the infrastructure and experience of money. RarefiedTech’s own fintech category reflects the diversity of this field, covering multiple technologies and trends rather than treating fintech as a single product or concept.
The most important lesson is that fintech is not simply about replacing traditional financial services with digital alternatives. It is about redesigning how financial services work. Banks, startups, technology companies, payment providers, regulators, and consumers all influence this process. Some innovations will succeed because they solve genuine problems; others will disappear because technology alone cannot compensate for poor design, weak security, unclear value, or inadequate trust.
For readers exploring on rarefiedtech.com fintech, the opportunity is to look beyond headlines and understand the underlying forces. Digital finance is becoming faster and more integrated, but its long-term success will depend on security, transparency, accessibility, responsible AI, thoughtful regulation, and genuine consumer value. The future of finance will not be shaped by technology in isolation. It will be shaped by how intelligently society chooses to use that technology.
Frequently Asked Questions About on rarefiedtech.com fintech
1. What does “on rarefiedtech.com fintech” refer to?
on rarefiedtech.com fintech refers to fintech-related information and coverage associated with RarefiedTech.com. The website has a dedicated fintech category covering developments across financial technology, including digital payments, lending, software, trading, and emerging technologies.
2. What is fintech in simple terms?
Fintech means using technology to deliver, improve, automate, or manage financial services. Examples include mobile banking, digital wallets, online payments, automated investing, financial analytics, digital lending, and blockchain-based financial applications.
3. Why are digital payments important to fintech?
Digital payments make it possible to transfer and receive money electronically with greater speed and convenience. They can also help businesses automate transaction records, reach online customers, and support new forms of commerce.
4. How is artificial intelligence changing fintech?
AI can analyze financial data, detect potentially suspicious transactions, automate customer support, personalize financial experiences, and assist with risk assessment. Its effectiveness depends on data quality, system design, transparency, and appropriate human oversight.
5. Is blockchain the same as cryptocurrency?
No. Blockchain is a type of distributed-record technology, while cryptocurrency is a category of digital asset. Cryptocurrency can use blockchain technology, but blockchain has potential applications beyond cryptocurrencies.
6. Does fintech replace traditional banks?
Not necessarily. Fintech companies can compete with banks, but they can also partner with them or provide infrastructure that banks use. The modern financial ecosystem increasingly contains combinations of traditional institutions and technology-driven services.
7. Can fintech improve financial inclusion?
Yes, fintech can reduce certain barriers to financial services by enabling digital payments, remote account access, alternative financial products, and mobile-first experiences. However, meaningful inclusion also requires affordability, connectivity, digital literacy, security, and consumer protection.
8. What are the biggest risks associated with fintech?
Important risks include cybersecurity attacks, identity theft, fraud, privacy violations, algorithmic bias, excessive borrowing, technology failures, and regulatory uncertainty. Digital convenience does not eliminate financial risk, so users should evaluate services carefully.
9. Why is fintech regulation important?
Financial services affect people’s money and economic security, so appropriate regulation helps establish standards for consumer protection, security, transparency, and market integrity. Effective regulation can also provide clearer rules that encourage responsible innovation.
10. What should readers look for when following fintech trends?
Readers should look beyond hype and ask practical questions: What problem does the technology solve? Who benefits? What risks exist? How is user data protected? What regulations apply? And does the technology provide a meaningful improvement over existing alternatives? Those questions make fintech coverage more useful and easier to evaluate critically.